On Tuesday 3 November, borrowers on variable home loans were handed their fifth rate rise for 2026. Canstar estimates the move adds $92 a month for someone owing $600,000 with 25 years left to run, which takes the increase across the five rises since February to $456 a month.
The Reserve Bank’s decision, released at 2.30pm AEDT, takes the cash rate target to 4.85 per cent from 4.60 per cent. Six Board members backed the rise and three wanted a hold. Canstar says the rate is now the highest since 2008.
The Board gave one main reason.
“Given the revised inflation outlook and the continuing upside risks, the Board judged that a further tightening in financial conditions is warranted to support the return of inflation to target.”
How will you handle higher repayments?
Choose an answer, then select Vote.
What Canstar’s Numbers Assume
The $92 figure comes with conditions. Canstar published it on Monday 2 November, before the decision, on the assumption of a 0.25 point rise. It models an owner-occupier paying principal and interest, with 25 years remaining in February 2026, at the RBA average variable rate. It also assumes banks pass the rise on the month after, and its figures are changes to minimum repayments.
Canstar’s post-decision example is a $700,000 mortgage with 25 years left as of February. For a borrower who started 2026 on an average rate, the fifth rise could add $107 a month. Count the four earlier rises as well and Canstar puts the total at “more than $500 extra each month compared to January”, and “over $6,000” across a full year.
If banks pass the rise on in full, Canstar says the average owner-occupier variable rate goes to 6.74% and rates under 6% will disappear.
Bigger Loans Than in 2008
According to Canstar, the average new owner-occupier loan has nearly tripled, from $254,000 in November 2008 to $731,000 in the June 2026 quarter, up 188%.
Sally Tindall, Canstar’s data insights director, said on Monday 2 November, before the decision: “While interest rates could be returning to levels last seen almost two decades ago, today’s borrowers are carrying significantly more debt, making every 0.25 percentage point increase that much more painful.”
Some households have a cushion. APRA data cited by Canstar put money in offset accounts near record highs at $340.5 billion. Others do not: Westpac reported that 14% of its mortgage customers have no buffer in their loan.
The Board expects the strain to reach spending and building.
“Higher interest rates and falls in housing prices and turnover are expected to weigh on growth in dwelling investment and household consumption.”
The cooling market has already shown up in Victoria’s state revenue.
Macquarie Moves First
Macquarie Bank was the first Australian bank to announce changes after the decision, Savings.com.au reported. According to the bank, its variable home loan reference rates rise by 0.25% p.a. from 19 November 2026, and ongoing variable rates on its transaction and savings accounts go up by 0.25% from the same date.
Ben Perham, Macquarie’s Head of Personal Banking, explained the wait.
“With household budgets already feeling the strain, today’s decision by the RBA will be challenging for many Australians. To help our variable home loan customers prepare, we’re again waiting more than two weeks before this latest increase takes effect.”
ANZ, CBA, NAB and Westpac had not announced by late afternoon on Tuesday 3 November, according to Savings.com.au. Canstar says all four majors are officially predicting this will be the final rise of the cycle.
What It Means for Savers
Savers can gain from a rise, but not evenly. After the September rise, the maximum ongoing rate on bonus savings accounts went up by an average of 0.20% to 4.97% p.a., while the average base rate moved from 0.20% to 0.21% p.a., Canstar found. Its research shows 41% of customers with a bonus saver account miss the maximum rate each month.
Canstar finance editor Brooke Cooper put it this way. “Bonus rates are a bit like a gym membership,” she said. “A deal may look great on the day you sign up, but it only pays off if you actually turn up.”
Before the Letter From Your Lender Arrives
Canstar says a variable-rate borrower’s lender “will almost certainly be in touch soon”. Macquarie customers have until 19 November; the majors had not set a date.
For anyone struggling to keep up, Canstar lists the National Debt Helpline on 1800 007 007.
This article is general information, not financial advice.
More finance coverage is in our Financial archive.
Sources: Reserve Bank of Australia, “Statement by the Monetary Policy Board: Monetary Policy Decision”, Media Release 2026-30, 3 November 2026 (https://www.rba.gov.au/media-releases/2026/mr-26-30.html); Canstar, “Higher rates, bigger debt: average borrower faces $456 increase in 2026”, 2 November 2026 (https://www.canstar.com.au/news/higher-rates-bigger-debt-average-borrower-faces-456-increase-in-2026/); Canstar, “Savers warned about ‘leaving money on the table’ after fifth RBA hike”, 3 November 2026 (https://www.canstar.com.au/news/rba-cash-rate-november-2026-hike-25/); Macquarie Bank, “Macquarie Bank’s response to the RBA’s interest rate decision”, 3 November 2026 (https://www.macquarie.com/au/en/about/news/2026/macquarie-banks-response-to-the-rba-interest-rate-decision-november.html); Savings.com.au, “LIVE RBA November Cash Rate Decision”, 3 November 2026 (https://www.savings.com.au/news/rba-november-2026-cash-rate-live-updates)
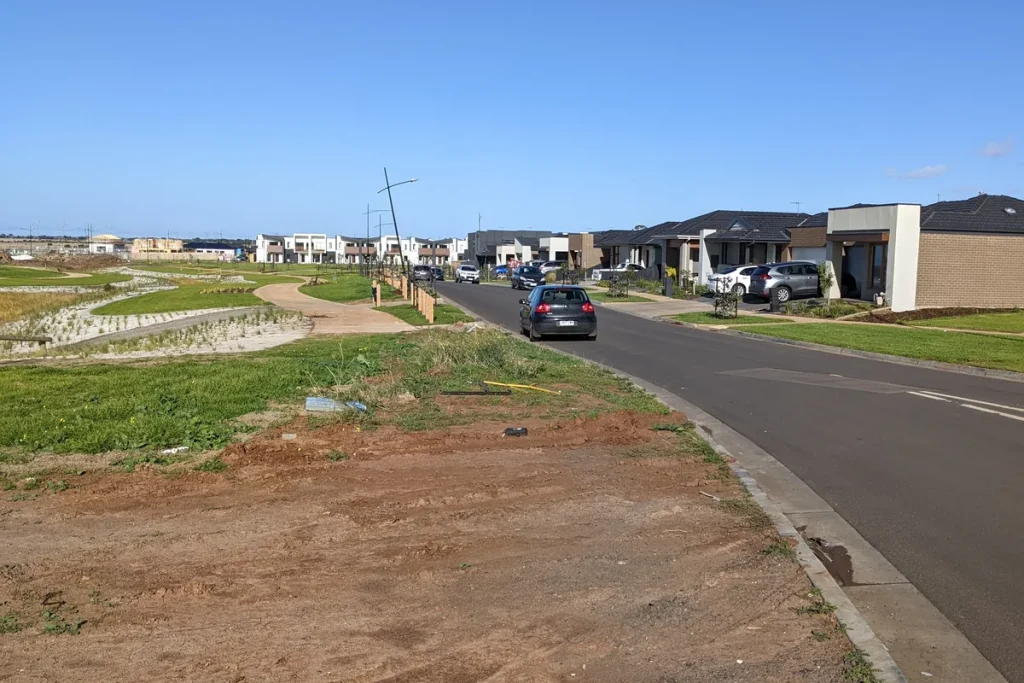
Photo: Philip Mallis, CC BY-SA 4.0, via Wikimedia Commons.
New homes along a street in Deanside, on Melbourne’s western fringe, in May 2023. Used for illustration: no household shown is part of this report.